
- Posted on 14 Oct 2026
- 23-minute read
By Frank Yuan and Elena Collinson
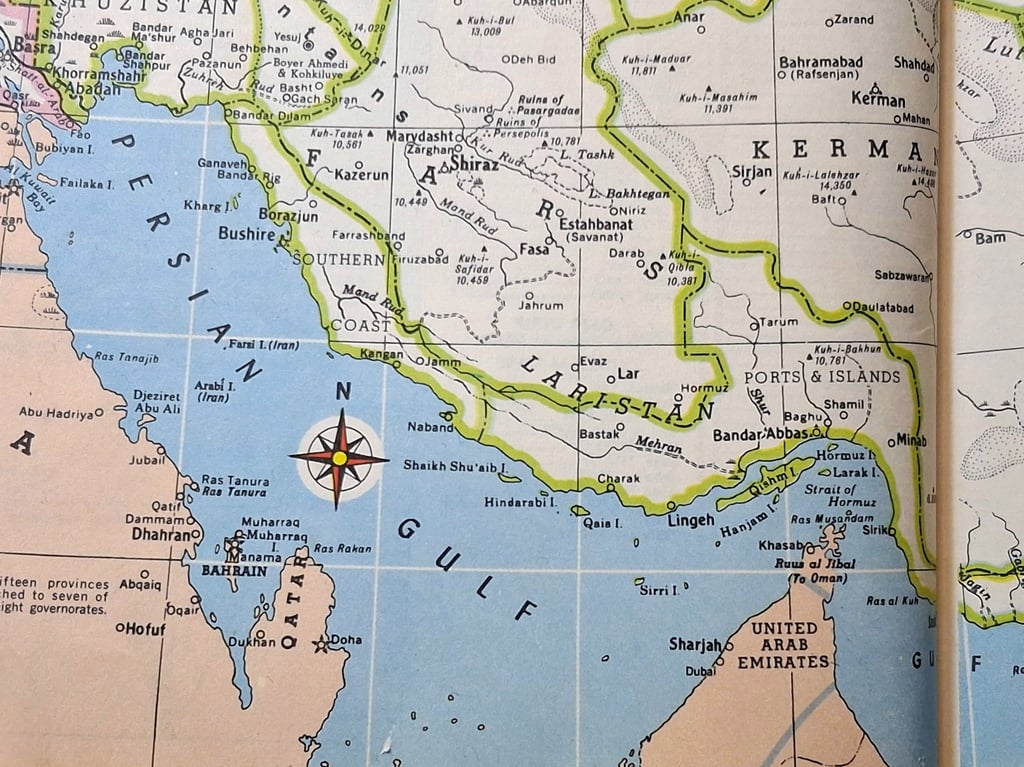
The disruption to global energy markets caused by the conflict around the Strait of Hormuz has highlighted vulnerabilities that extend well beyond the immediate question of oil and gas supply. It has also brought into sharper focus the different sources of energy strength and vulnerability of the United States and the People’s Republic of China (PRC), namely, Washington’s abundant hydrocarbon resources and expanding energy exports, and Beijing’s combination of stockpiling, supply diversification, electrification and strength in key clean energy technologies.
This UTS:ACRI Analysis examines how these different sources of energy leverage are shaping US-PRC strategic competition. It considers their respective strengths and constraints before examining the implications for Australia. As a major exporter of LNG and minerals, a close US ally, a major trading partner of the PRC and an importer of refined petroleum products, Australia is both exposed to changes in the global energy system and potentially well placed to benefit from them.
Introduction
The tension between Australia’s crucial economic links with the People’s Republic of China (PRC) and its increasingly close alliance with the United States is well understood. The crisis around the Strait of Hormuz has exposed another vulnerability. Australia is a major natural gas exporter while remaining highly dependent on imported refined petroleum products. In 2024-25, imports accounted for 80.8 percent of Australia’s refined petroleum consumption, even as 73.8 percent of domestic natural gas production was exported. This reflects a broader imbalance in Australia’s energy position. The country is a major net energy exporter overall but remains highly dependent on imports for the liquid fuels most exposed to maritime disruption. In 2024-25, Australia exported more than six times as much energy as it imported – 15,067 petajoules (PJ) compared with 2,311 PJ – with crude oil and refined petroleum products accounting for 99.4 percent of those imports.
Against this backdrop is a less appreciated development – the competition between Beijing and Washington in the energy sector. Its significance has grown with the Trump administration’s pursuit of an ‘energy dominance’ strategy.
‘Energy dominance’ was set out explicitly in the US' 2025 National Security Strategy, which stated:
Expanding our net energy exports will also deepen relationships with allies while curtailing the influence of adversaries… and – when and where necessary – enables us to project power.
The strategy also rejected ‘“climate change” and “Net Zero” ideologies’ for ‘subsidis[ing] our adversaries’.
The PRC presents an obvious challenge to this conception of energy power. It is the dominant global manufacturer of several clean energy technologies, including solar photovoltaics, batteries and electric vehicles, and a major exporter of them. Where US energy leverage rests heavily on control over abundant hydrocarbon production, the PRC’s strength increasingly rests on the technologies that allow countries to reduce their dependence on hydrocarbons in the first place.
1. US-PRC energy competition
1.1 Hormuz tests US ‘energy dominance’
The Iran War and the disruption around Hormuz have provided an early test of these competing strengths. At first glance, the war appears to have exposed limits to ‘energy dominance’.
The analysis that follows focuses primarily on a prolonged but partial disruption to Gulf energy flows rather than a complete and sustained closure of the Strait. This broadly reflects the course of the conflict. Flows through Hormuz fell sharply following the outbreak of war but did not cease, and have subsequently recovered to around three-quarters of pre-war crude volumes, while producers and shippers have adapted through alternative routes and changing shipping arrangements. A simultaneous severe disruption at Hormuz and Bab el-Mandeb would represent a more acute scenario by constraining two major maritime routes used to move Middle Eastern energy exports.
The PRC, the world’s largest crude oil importer, demonstrated resilience during the initial shock. It managed to cut its crude oil imports by about one-third during the second quarter of 2026 without the severe immediate disruption that might have been expected for an economy so dependent on foreign oil. The adjustment was not costless, however. Higher energy prices added to already substantial economic headwinds, while part of the PRC’s ability to reduce imports reflected lower refinery throughput, reduced stockbuilding and, increasingly, drawdowns from accumulated inventories.
The US, despite being a major net petroleum exporter, has also demonstrated continuing exposure to global energy supply disruption, drawing down its strategic petroleum reserves while facing public anger over elevated fuel prices. Its Strategic Petroleum Reserve fell to around 284 million barrels by late September 2026, its lowest level since 1982. On September 29 2026, the US government announced that it would offer to loan a further 40 million barrels from the reserve as part of the wider International Energy Agency response to the energy shock.
This illustrates an important limitation of the ‘energy dominance’ concept: even abundant domestic petroleum production does not insulate consumers from global oil-price volatility or supply disruption. US petroleum prices remain closely linked to internationally traded crude prices. Natural gas is different. The US gas market was historically much more insulated from international prices, although the rapid growth of LNG exports has increasingly connected domestic and international gas markets.
Yet this vulnerability should not obscure the US’ underlying energy advantage. It produces more energy than it consumes overall. In 2025, US energy exports were around 50 percent higher than energy imports, leaving the country a substantial net energy exporter. This does not make the US immune to global energy shocks as domestic petroleum prices remain linked to international oil markets and the country still imports particular crude grades. But it gives Washington considerably greater flexibility in responding to disruptions than countries that depend heavily on imported hydrocarbons.
Washington has also secured expanded access to Venezuelan crude. An agreement announced in August 2026 gives US-backed interests access to a substantial portion of Venezuela’s oil reserves and is intended to direct additional crude towards the US market. The composition of Venezuelan heavy crude complements much of the US Gulf Coast refining system. However, years of underinvestment, infrastructure constraints and uncertainty around the implementation of the agreement mean that substantially increasing Venezuelan output will take time.
The US has an even greater advantage in natural gas as the world’s largest liquefied natural gas (LNG) exporter. It has the option of insulating its domestic supply through some forms of export restriction, though doing so would impose costs on its allies and raise questions about the reliability of the US as a supplier. The energy problem for Washington is thus one of politics and prices, rather than underlying resource availability.
The PRC faces a different set of constraints. The scale of the PRC’s oil import cut-back exceeds the savings achievable simply by pausing stockbuilding, reducing exports of refined oil products, or a combination of the two. Lower refinery throughput and weaker end-user demand also contributed to the adjustment – but these reflect less-than-ideal economic conditions rather than deliberate policy. In other words, the PRC has likely been tapping into its commercial and/or strategic reserves, running down part of the buffer against future shocks, however substantial its accumulated inventories may be.
More recent data reinforce this interpretation. In August 2026, Chinese refineries processed around 13.91 million barrels per day of crude, compared with approximately 13.27 million barrels per day available from imports and domestic production, implying an inventory draw of about 640,000 barrels per day. This was the third monthly draw in four months.
Beijing has also allowed domestic fuel prices to rise, complicating its efforts to rebalance its economy by boosting consumption.
A rapid return of PRC oil imports to pre-conflict levels would nevertheless add substantial demand to a constrained global oil market and could place renewed upward pressure on prices. Higher oil prices could, in turn, weigh disproportionately on oil importing developing economies, including markets of growing importance to Chinese exporters, creating an additional indirect cost for the PRC.
1.2 The PRC’s response: Diversification and electrification
Fundamentally, the PRC remains reliant on hydrocarbon imports. Prior to the Iran War, about two-thirds of the PRC’s oil supply and one-fifth of its natural gas supply arrived by sea (authors’ calculations). Pipeline imports from Russia and Central Asia help to offset maritime vulnerability but cannot readily substitute for seaborne supply at scale, while capacity expansion will be slow and limited. The proposed Power of Baikal (formerly Power of Siberia 2) pipeline, for example, would provide a major additional source of Russian gas, but key questions, including pricing and a firm implementation timetable, remain unresolved.
In recent years, the PRC has also significantly expanded its oil inventories, which, by 2026, could cover about 120 days of net crude oil imports at 2025 levels. Estimates should nevertheless be treated cautiously because the PRC does not publish comprehensive data on strategic and commercial stocks.
Beijing’s most visible achievement has been the rapid rollout of renewables and transport electrification, allowing the PRC to rely more heavily on resources within its own territory. The continued construction and upgrading of coal-fired power plants – despite the lower utilisation rates of parts of the existing fleet – can also be understood partly in terms of domestic energy security and system redundancy.
The scale of the PRC’s continued dependence on coal is nevertheless substantial. Coal still provided around 50 percent of its electricity generation in the first six months of 2026, down from 65.5 percent in 2016, while almost 80 gigawatts (GW) of new coal-fired capacity was commissioned during the previous year. Electrification is occurring alongside, rather than rapidly replacing, a still heavily fossil fuel-dependent energy system.
1.3 Exporting an alternative energy pathway
The PRC’s green manufacturing boom is also extending these effects beyond its borders. EVs reduce oil demand, while batteries increasingly compete with gas-fired peaking plants in providing short-duration grid flexibility.
The effect on oil demand is already material. The International Energy Agency estimates that the global EV fleet displaced around 1.7 million barrels per day of oil consumption in 2025, including around one million barrels per day in the PRC alone. Under current policy settings, global displacement could reach around five million barrels per day by 2030.
Some developing countries may well decide to forgo parts of the hydrocarbon-intensive phase of development, saving resources that would otherwise be spent on costly hydrocarbon infrastructure, while reducing exposure to supply shocks. Ethiopia, for instance, banned imports of internal combustion engine vehicles in 2024, partly to reduce expenditure on imported oil.
Even without considering energy security, continued improvements in the cost-efficiency of green technologies will make them increasingly attractive.
Beijing’s green industrial policy thus provides countries with an alternative pathway that can reduce dependence on imported hydrocarbons and, in doing so, potentially weaken one basis of Washington’s ‘energy dominance’. But this pathway can also substitute one form of external dependence for another. The PRC accounted for more than 80 percent of global battery cell production in 2025, while mineral processing and clean technology supply chains remain highly concentrated.
Still, technology dependence differs from fuel dependence. Once installed, most clean energy technologies do not require the same continuous flow of imported inputs as oil or gas. Concentrated technology and mineral supply chains can still create vulnerabilities, but those vulnerabilities operate differently from dependence on an uninterrupted flow of imported fuel.
This process also has practical limits. Oil remains difficult to replace in aviation and petrochemicals, natural gas remains important as a feedstock for fertiliser and in other industrial applications, and hydrocarbons provide important by-products such as helium. Technological advances may provide partial substitutes in some applications, but even under ambitious transition scenarios hydrocarbons continue to play a role in the global energy and petrochemical system.
Nonetheless, reducing exposure to imported energy can materially reduce a country’s strategic vulnerability. Whether it reduces overall external vulnerability will also depend on the diversity and resilience of the technology and mineral supply chains on which the alternative energy system relies.
The shift between these energy systems is therefore neither immediate nor wholly zero-sum. Many countries will continue to combine hydrocarbons, renewables, storage and electrification. However, the infrastructure required by different energy systems is expensive and long-lived. Developing countries in particular are unlikely to pursue every competing infrastructure system at full scale; even some developed countries could eventually transition towards an ‘electrostate’ model, in which electricity replaces a greater share of direct fossil fuel consumption.
As such, an important feature of the transition is path dependence. Investment in one energy system can reduce the economic case for competing infrastructure and shape a country’s patterns of energy supply for decades.
Recent PRC commodity demand illustrates the complexity of this transition. The PRC continues to consume large quantities of conventional fuels even while rapidly expanding electrification and clean energy manufacturing. At the same time, imports of industrial metals including bauxite, nickel, chrome, lithium and manganese have risen strongly, consistent with growing demand from manufacturing, batteries, renewable energy equipment and electricity infrastructure. The transition is consequently better understood as an overlap of old and new energy systems.
1.4 The limits of energy leverage
There are other constraints on Washington’s ability to translate ‘energy dominance’ into geopolitical leverage.
The PRC has substantial financial capacity to purchase imported hydrocarbons because of its sizeable trade surplus and foreign exchange reserves. It also possesses substantial shipping capacity and can reduce its reliance on Western shipping and insurance providers. These advantages can blunt some of the practical effects of sanctions-related restrictions on securing imported fuel, although they do not eliminate sanctions risk or physical vulnerabilities associated with maritime chokepoints, shipping capacity and the availability of particular fuel grades.
Short of direct attacks on shipping, with the substantial escalation risks that would entail, seriously restricting the PRC’s fuel supply would require the cooperation of a large share of the world’s hydrocarbon producers. Even if Washington dictated trade across the Americas, the region accounts for less than 40 percent of global production in either crude oil or natural gas. Russia and Central Asia provide the PRC with important non-maritime alternatives, although existing and planned pipeline capacity could not simply substitute for all of the PRC’s seaborne oil and gas requirements.
If asked to join economic measures against the PRC, major Gulf producers would also have commercial and geopolitical interests of their own to consider. Measures that substantially reduced Chinese purchases could come at the expense of their own hydrocarbon market share and constrain their room for manoeuvre between Beijing and Washington.
Historical experience illustrates the difficulty of coordinating such policies among allies and partners. During the Cold War, for example, Washington was unable to secure Australian or Canadian agreement to weaponise their grain sales to the PRC.
At present, Beijing’s dominant position in critical mineral processing and other strategically important supply chains also gives it leverage of its own.
Nonetheless, Washington retains powerful advantages in hydrocarbon production and exports and has incentives to exploit areas in which it remains particularly strong. The gradual and – at least for now – incomplete nature of the energy transition means that hydrocarbon leverage remains an asset. [FY2] In a potentially more bifurcated international order, where a ‘China bloc’ in aggregate imports hydrocarbons, supply shortages could still put Beijing on the back foot. The domestic political significance of fossil fuel industries in the US also impels Washington to adopt policies that protect their markets both at home and abroad.
US-PRC energy competition is likely to survive Donald Trump’s presidency. Joe Biden’s administration in the early 2020s pursued industrial policies supporting domestic manufacturing of batteries, electric vehicles, solar equipment and critical mineral supply chains, albeit with very different stated climate and energy objectives. The particular policy mix may therefore change between administrations without removing the strategic importance attached to energy technologies and supply chains.
If a future US administration again took an interest in renewable energy, it might also find cooperation with the European Union (EU) more politically and strategically attractive than dependence on the PRC, although the commercial viability of such diversification would ultimately depend on cost, scale and the competitiveness of alternative supply chains.
Clashing interests on energy are thus intertwined with the broader strategic competition between the PRC and the US.
At the same time, recent developments show that the competition does not amount to complete economic separation. During President Xi Jinping’s September visit to Washington, the PRC committed to importing at least 10 million tonnes of US coal in both 2027 and 2028, while the two governments continued discussions over US concerns about access to PRC-controlled rare earth and critical mineral supply chains.
The episode illustrates the coexistence of strategic rivalry and material interdependence.
2. Implications for Australia
Australia sits across both sides of this competition. It is a major hydrocarbon exporter, a significant supplier of minerals required for electrification, an ally of the US and a major trading partner of the PRC. At the same time, its dependence on imported refined petroleum products creates a significant domestic energy security vulnerability.
Changes in the balance between hydrocarbons and electrification therefore present both risks and opportunities for Australia’s export markets, domestic energy system and foreign policy.
2.1 LNG: Short-term gains, longer-term competition
Australia’s natural gas exports are caught in the crossfire. The US has been expanding production and exports, heightening competition for Australia-based producers. Other major gas exporters are also seeking additional markets. The sharp decline in Russian pipeline gas deliveries to Europe has increased European reliance on LNG, creating additional demand for non-Russian suppliers even as Russia seeks alternative markets for its own gas. At the same time, new Canadian LNG capacity is opening an additional source of supply to Asian buyers.
On the demand side, the PRC – and many other LNG importers – has strong incentives to reduce vulnerability to expensive or geopolitically exposed LNG supplies.
In 2025, the PRC’s LNG imports fell by 14 percent year-on-year. They fell another 12 percent year-on-year between March and June 2026 as the Hormuz disruption, elevated spot prices, stronger domestic production and demand-side adjustment reduced purchases.
These developments do not necessarily indicate that the PRC’s LNG demand has permanently peaked. The PRC has continued to develop LNG import infrastructure, while lower prices could again support demand once additional global supply becomes available. The more cautious long-term conclusion is that LNG faces increasing competition within the PRC’s energy system.
For Australian producers, meanwhile, the short-term effect of the Middle East disruption is favourable. The loss of Gulf supply contributed [EC3] to a four percent year-on-year decline in global LNG production between March and June, tightening global LNG availability. Higher oil prices also supported revenues under oil-linked LNG contracts. Together, these effects increased the value of geographically diversified supply, including from Australia.
The Australian government’s September 2026 Resources and Energy Quarterly forecasts LNG export earnings rising from $57 billion in 2025-26 to $70 billion in 2026-27 due to higher prices, before declining to about $42 billion in real terms by 2030-31 as Middle East supply and trade conditions normalise, while US supply grows and Qatari output recovers.
Australia therefore faces a combination of short-term support for LNG earnings and longer-term competition.
2.2 Gas, electrification and energy security
For Australia, these shifts matter not only for LNG exports but also for the longer-term role of gas within the global energy system.
Economic and energy security considerations are also making alternative technologies increasingly competitive against natural gas in some applications.
As grid-scale batteries become cheaper and safer, they are becoming increasingly competitive with new gas-fired generation for short-duration flexible power. CSIRO’s 2026 GenCost analysis found that falling battery costs and rising gas turbine costs are making batteries increasingly attractive for flexible generation, including in place of gas peakers during short-duration evening peaks. Gas is nevertheless expected to retain a limited but important firming role, contributing around 3-7 percent of generation by 2050.
The boom in AI data centres has both increased demand for US gas and created long backlogs for gas turbines. This poses another disadvantage for developers seeking rapidly deployable generation capacity.
Electrification affects different fuels differently. Transport electrification primarily reduces oil demand, while electrification of heating and some industrial processes can reduce natural gas consumption. Gas used as an industrial feedstock is less directly exposed to electrification than many energy uses of gas.
Energy security will also shape how countries source the gas they continue to consume.
If oil and gas supplies are increasingly subject to geopolitical disruption, energy security concerns are likely to encourage greater diversification of supply, including domestic production and, where geography permits, pipeline imports. For countries connected to reliable neighbouring producers and facing little risk of targeted attacks – either due to location or deterrence – pipelines can reduce exposure to maritime chokepoints. The PRC, for instance, has invested in gas pipelines from Central Asia and Russia, with preparations to build a second trans-Siberian pipeline. It has also intensified hydrocarbon exploration on land.
But pipelines replace maritime dependence with dependence on fixed infrastructure and particular suppliers. LNG has the opposite trade-off. It is exposed to maritime disruption but gives buyers the ability to diversify cargoes across producers where contractual terms permit.
The Hormuz crisis has shown the value of both diversification and redundancy rather than demonstrating that one model is inherently more secure.
Another disadvantage of natural gas is the cost and complexity of storing it compared with oil and coal. In importing countries, governments and companies may prefer, all else equal, energy commodities for which they can build up sizeable buffers against supply disruptions and price spikes.
Where gas is difficult to replace as an industrial feedstock, resilience may instead involve diversifying suppliers or stockpiling intermediate and final products such as ammonia, fertilisers and plastics.
One possible strategic consequence of the PRC’s clean technology exports is therefore to help trading partners reduce their exposure to imported hydrocarbons. In turn, this could indirectly reduce the leverage available to major hydrocarbon exporters, including the US.
2.3 Mining: The electrification opportunity
For Australia’s mining sector, these trends could create significant opportunities.
Building new and redundant capacity in energy production, transport and storage requires large quantities of metals. The same is true for electrification. A Rio Tinto fact sheet notes, for example, ‘Electric vehicles, renewable power generation, battery storage, transmission networks and electrified industries all require significantly more metals than the systems they replace.’
Copper is one of the clearest examples. Australia’s Department of Industry forecasts copper export earnings increasing from $14 billion in 2025-26 to $19 billion in real terms by 2030-31, supported by demand from clean energy technologies, data centres and electricity infrastructure. Total real critical minerals export earnings, including lithium and nickel, are forecast to rise from around $17 billion to $25 billion in 2026-27, before easing to $22 billion in real terms by 2030-31.
The PRC’s steel sector illustrates how the composition of commodity demand can also change.[FY4] [EC5]
PRC crude steel production fell from 1.065 billion tonnes in 2020 to 960.8 million tonnes in 2025 — a decline of roughly 10 percent — as the property downturn weighed on domestic demand. Rather than producing a commensurate collapse in steelmaking, however, weaker property-related demand was partly cushioned by growing steel consumption in manufacturing, while exports provided an additional outlet for production. According to the China Iron and Steel Association, manufacturing’s share of steel consumption rose from 42 percent in 2020 to 51 percent in 2025, overtaking construction for the first time. Steel exports, meanwhile, reached a record of more than 119 million tonnes.
The experience highlights a distinction for Australia. New sources of demand associated with manufacturing, electrification and infrastructure can offset some weakness in traditional sectors, but they need not fully replace it. The benefits of the energy transition for Australian mining will therefore depend on the changing mix of commodity demand as much as on its overall growth.
Australia’s abundant mineral resources and reserves of copper, cobalt and lithium similarly position it to supply raw materials for wires, batteries and other equipment.
The opportunities created by electrification should therefore be assessed commodity by commodity. Technology substitution, recycling, additional global supply and commodity price cycles mean that electrification will not produce identical outcomes across all minerals. Nor does resource endowment automatically guarantee that Australia will capture a proportionate share of the downstream economic value.
Whether more processing occurs in Australia will depend heavily on project economics. Relevant conditions include access to competitively priced energy, water and enabling infrastructure; specialised processing technology and skills; sufficient scale and capital; and the ability to secure long-term offtake, equity and debt finance. Australia’s Critical Minerals Strategy identifies several barriers to downstream projects, including complex mineralogy and specialised processing requirements, significant capital and energy needs, remote infrastructure constraints and concentrated or opaque markets.
The government is already moving to improve these economics. From July 1 2027, the Critical Minerals Production Tax Incentive will provide a refundable 10 percent tax offset on eligible Australian processing expenditure for minerals on the Critical Minerals List, for up to 10 years per registered processing activity.
Much of the processing of minerals used in clean energy technologies nevertheless remains concentrated in the PRC. The International Energy Agency’s 2026 Global Critical Minerals Outlook notes that the PRC remains the dominant refiner for most key energy minerals, with its share exceeding 90 percent for some materials including graphite, manganese and rare earths. Australia’s opportunity will depend not only on higher demand for its resources, but on whether domestic policy settings and international market conditions allow commercially viable processing and other downstream capabilities to develop domestically or through diversified supply chains.
2.4 A green industrial opportunity
Energy security considerations could also support the development of Australian exports of green energy-intensive goods.
This vision entails using Australia’s abundant renewable resources to produce globally traded commodities whose manufacture requires large quantities of energy, including green iron, aluminium and renewable hydrogen-derived ammonia and fertilisers.
For some importing countries, obtaining these materials from reliable suppliers could allow them to reduce the amount of energy-intensive processing undertaken domestically while maintaining stockpiles of the resulting products.
Green iron has become a particular focus of Australian industrial policy. In February 2025, the Australian government established a $1 billion Green Iron Investment Fund to support early mover projects and attract private investment, with up to $500 million earmarked for the transformation of the Whyalla steelworks and at least $500 million available for projects elsewhere in Australia. In August 2026, Fortescue produced its first hot metal at its Christmas Creek green iron facility in the Pilbara, providing an early demonstration of efforts to process a greater share of Australian iron ore domestically using lower-emissions technologies.
Cooperation with the PRC is increasingly being pursued as part of this agenda. During Prime Minister Anthony Albanese’s July 2025 visit to the PRC, Australian and Chinese representatives participated in a Steel Decarbonisation Roundtable in Shanghai. Albanese noted that Australian miners supply almost 60 percent of the PRC’s iron ore imports, while the PRC produces more than half of the world’s steel. The two governments also agreed to establish an Australia-China Policy Dialogue on Steel Decarbonisation.
Commercial and technical cooperation is developing alongside this policy engagement. In September 2026, BHP and China Baowu renewed their steel decarbonisation partnership for a further five years, including work on the use of Pilbara ores in direct reduced iron and electric smelting furnace technologies. Such initiatives create a potential pathway through which Australian resources and renewable energy advantages could be combined with the PRC’s steelmaking scale and technical capabilities.
There is, however, a tension in this model. Australia is seeking to move further downstream and retain a larger share of processing, investment and industrial capability onshore, while the PRC is simultaneously seeking greater consolidation and coordination within its own steel industry. Beijing’s steel capacity replacement rules introduced in 2026 encourage consolidation by requiring more existing capacity to be retired for new capacity to be constructed, while providing more favourable treatment for substantive mergers. The 10 largest PRC steel producers accounted for around 43 percent of national output in 2025, suggesting there remains considerable scope for further concentration.
Centralisation is also occurring upstream. The state-backed China Mineral Resources Group has become the central negotiator for a substantial share of the PRC’s imported iron ore. By August 2026, it was negotiating for more than half of the country’s annual import volumes. Some steelmakers continue to retain their own negotiating rights, although CMRG has sought to persuade them to cede those rights in order to further consolidate purchasing power. These developments show that Australia’s ambition to capture more processing value will unfold alongside Beijing’s efforts to increase coordination and bargaining power across its own steel and raw material supply chains.
The two objectives are not necessarily incompatible. Greater concentration among PRC steelmakers could also result in [FY6] [EC7] a smaller number of large counterparties capable of supporting long-term technology, investment or offtake partnerships with Australian projects. The commercial opportunity for Australia will depend on whether such arrangements can share value across the supply chain while giving PRC producers access to competitively priced, lower-emissions iron inputs.
Green iron therefore illustrates the broader tension running through Australia’s position in the energy transition: deeper economic integration with the PRC can help create markets, scale and technology partnerships for new Australian industries, while both countries are simultaneously seeking greater control over strategically important parts of their supply chains.
2.5 Strengthening Australia’s energy security
Australia also has an opportunity to improve its energy security by taking advantage of the expansion in green technologies.
Transport electrification will make Australia less dependent on imported oil. This matters because imports met 80.8 percent of refined petroleum consumption in 2024-25.
Electrification would not entirely obviate the need to import and stockpile refined fuel. Aviation, heavy transport, defence and other activities will continue to rely on liquid fuels for some time. But a less oil-intensive economy could operate for longer on the same volume of fuel reserves in the event of import loss.
The issue has become more immediate during the 2026 Middle East crisis. The Australian government has committed to establishing a $3.2 billion Australian Fuel Security Reserve holding around one billion litres of diesel and jet fuel, alongside higher minimum stockholding requirements and other measures intended to strengthen fuel supply resilience.
These approaches are complementary. Australia can increase the physical buffer against disruption while simultaneously reducing the quantity of imported fuel required by the economy. Transport electrification can also reduce consumer exposure to global petroleum price shocks.
Grid stability can also benefit from greater diversity of domestic generation and storage. Coal- and gas-fired generators can lose efficiency during extreme heat, a growing concern as climate change continues. Renewable generation and batteries have different weather, transmission and storage vulnerabilities.
2.6 Navigating trade, technology and security
To make the most of these opportunities, Australia has an interest in maintaining a generally open international trade system and its reputation as a reliable supplier.
Where critical mineral supply chains are not acutely security-sensitive, Australia has an interest in limiting unnecessary spillovers from diplomatic and geopolitical disagreements into commodity trade.
This was partially achieved during the nadir of its relationship with the PRC in the early 2020s, when the iron ore trade remained largely insulated from the trade barriers and coercive measures imposed on a range of other Australian exports.
Australia and the PRC continue to have areas of converging economic interest in expanding green industrial ecosystems. At the same time, Australia’s alliance with the US and wider security relationships create incentives to diversify strategically important supply chains away from concentrated PRC processing and manufacturing capacity. This presents a trade-off. PRC scale and manufacturing efficiency can lower the cost of electrification, while heavy concentration in particular technologies and processing stages can itself create vulnerabilities.
Economic dependence can create serious national security vulnerabilities, but the nature and severity of those risks vary across sectors, technologies and supply chains. Distinguishing strategically significant exposure from commercial dependence that can be managed through diversification, regulation or other safeguards will therefore become increasingly important.
Connected vehicles illustrate the difficulty of drawing this line. The US already restricts certain connected vehicle hardware and software with a sufficiently strong nexus to the PRC or Russia on national security grounds. In Australia, scrutiny intensified in September after an ABC Four Corners investigation found that Leapmotor EVs sold in Australia use cameras made by Dahua Technology, whose surveillance equipment had previously been removed from Defence and other federal government sites over security concerns.
While the finding does not establish that those components create the same risks in consumer vehicles as in sensitive government settings, it does sharpen the question of whether safeguards are keeping pace as vehicles become more connected and data intensive. Home Affairs Minister Tony Burke has said that some risk-based restrictions are already applied at sensitive Australian sites.
The challenge for Australia is to distinguish risks common to connected technologies from additional risks associated with particular vendors, ownership structures or jurisdictions, and to apply safeguards proportionate to the exposure.
Conclusion
Energy competition between the US and the PRC, together with the heightened global importance of energy security, will have mixed effects on Australia.
Australian LNG producers can benefit from periods of supply disruption and from demand for geographically diversified energy supplies, while facing stronger longer-term competition from new LNG capacity and alternative energy technologies.
Copper and some critical minerals could benefit from increased investment in electrification, electricity networks and supply chain resilience, although the gains will vary significantly by commodity.
Australia’s abundant renewable resources may also allow it to export a greater volume of energy-intensive processed commodities alongside its traditional exports of fuels and raw materials.
At home, Australia has an opportunity to reduce one of its longstanding energy vulnerabilities by decreasing its reliance on imported refined petroleum products while maintaining adequate strategic stocks.
At the same time, these economic opportunities intersect with strategic choices. Australia’s interests do not fit neatly within either a US-centred hydrocarbon system or a PRC-centred clean technology system. It has important economic interests in both, as well as in the diversification of energy supply chains.
Few countries are as well-endowed as Australia to navigate these changes, given its combination of hydrocarbons, renewable energy resources, mineral wealth and established trading relationships across Asia.
Realising those advantages will require adjustment by both government and business. The key considerations are likely to be energy security, reliability as a supplier, commercially viable opportunities in electrification and energy-intensive exports, and the management of technology and supply chain risks in line with Australia’s economic and national security interests.
AUTHOR
Frank Yuan
Adjunct Fellow, Australia-China Relations Institute, University of Technology Sydney
AUTHOR
Manager, Research Analysis, Australia-China Relations Institute, University of Technology Sydney
News
The US and China cannot slow the AI race, but they can make It safer
The United States does not need to trust China, share frontier models with China, or slow its own AI development to have a national security interest in AI...
News
Australia-China Weekly Brief: October 2026 issues
The Australia-China Weekly Brief by the Australia-China Relations Institute at the University of Technology Sydney (UTS:ACRI) tracks key developments in...
News
Whose security counts in the Pacific?
While climate-related spending gets criticised, billions forked out for security and strategic engagement gets framed as for the “national interest”.
News
In conversation with Mr Ted O'Brien MP
On October 7 2026, the Australia-China Relations Institute at the University of Technology Sydney (UTS:ACRI) welcomed Mr Ted O'Brien MP, Australia’s Shadow...
News
The US and China cannot slow the AI race, but they can make It safer
The United States does not need to trust China, share frontier models with China, or slow its own AI development to have a national security interest in AI...
News
Australia-China Weekly Brief: October 2026 issues
The Australia-China Weekly Brief by the Australia-China Relations Institute at the University of Technology Sydney (UTS:ACRI) tracks key developments in...
News
Whose security counts in the Pacific?
While climate-related spending gets criticised, billions forked out for security and strategic engagement gets framed as for the “national interest”.
News
In conversation with Mr Ted O'Brien MP
On October 7 2026, the Australia-China Relations Institute at the University of Technology Sydney (UTS:ACRI) welcomed Mr Ted O'Brien MP, Australia’s Shadow...